Key Man Risk
Thanks to Jensen Huang, “key man risk” is perhaps a top of mind concern among many investors over the last week. For a solo entrepreneur like me, I have actually been thinking about this for a while since this risk is pretty close to home at MBI Deep Dives.
Thanks to Jensen Huang, “key man risk” is perhaps a top of mind concern among many investors over the last week. For a solo entrepreneur like me, I have actually been thinking about this for a while since this risk is pretty close to home at MBI Deep Dives. I did wonder what would happen to MBI Deep Dives if I got hit by a proverbial bus. I actually had a conversation about this with my wife and I already let her know the “next steps”.
While I certainly hope she would not have to think about these steps decades into the future, let me share with all of you as well what I would like to happen if the “key man” behind MBI Deep Dives is no longer around.
My wife would reach out to three or four friends (who are investors by profession) she knows I trust, and those friends would interview five to ten analysts. Whoever they pick would take over MBI Deep Dives and run it going forward, and in return they would pay 20% royalties to my family.
MBI Deep Dives is obviously not the only place where I think about key man risk. Since I manage my own and my family’s savings, I think about it for every business I own. By now everyone knows what happened at Nvidia, so I won’t repeat the saga here. I find it more interesting to think through how much of a company’s value really comes from the person running it.
Ed Catmull, the co-founder of Pixar, was quite influential in shaping my philosophy on this topic. Catmull wrote in an HBR essay back in 2008:
A few years ago, I had lunch with the head of a major motion picture studio, who declared that his central problem was not finding good people—it was finding good ideas. Since then, when giving talks, I’ve asked audiences whether they agree with him. Almost always there’s a 50/50 split, which has astounded me because I couldn’t disagree more with the studio executive. His belief is rooted in a misguided view of creativity that exaggerates the importance of the initial idea in creating an original product. And it reflects a profound misunderstanding of how to manage the large risks inherent in producing breakthroughs.
He went further in Creativity, Inc., where he wrote that in all his years of asking that question, only one person had pointed out that it was a false choice. To him, the answer was obvious. “Ideas come from people. Therefore, people are more important than ideas.”
Indeed, I think that is why key man risk is real even at companies with tens of thousands of employees. We like to talk about strategy as if it were the output of a purely rational, scientific process, but companies are not run by AI, at least not yet. They are run by people whose beliefs, philosophy, personal quirks, and life experiences shape how they see the world, and in turn what they decide. When the person at the top changes, the ideas sometimes change with them.
Meta, my largest position, is arguably just as exposed to this as Nvidia was. Ironically, you could perhaps make the case that Meta’s stock would go up if Mark Zuckerberg left in the near term. Why? Well, let’s look at Microsoft. Frontier models are arguably a much more immediate risk to Microsoft’s business than to Meta’s. Meta’s family of apps is further away from that risk vector as of today, although I doubt it can stay immune forever. And yet Satya Nadella has largely chosen not to pursue training frontier models himself, and the market seems to prefer that decision a lot more. If the company more exposed to the risk has decided to sit out the frontier race, the case for a manager-led Meta doing the same looks even stronger. So if someone like Nadella took over Meta, stopped pursuing frontier models and shut down Reality Labs, Meta would be a lot more profitable in the near term, and perhaps after the initial dip in the stock post-Zuckerberg exit, pod shop analysts would be salivating at the rapid upward estimate revisions for the next couple of years.
I am not sure I believe it would be the right reaction over the long term for Meta.
When I first went through Facebook’s “red book” a few years ago, the following page made me pause. From the very early days, Zuckerberg has been skeptical about having a five-year plan. He was only sure about the next six months, but counter-intuitively he was also quite adamant about the next 30 years! If you remember this, it is easier to understand why Meta seems to frantically pivot from one thing to another as they navigate towards the future.
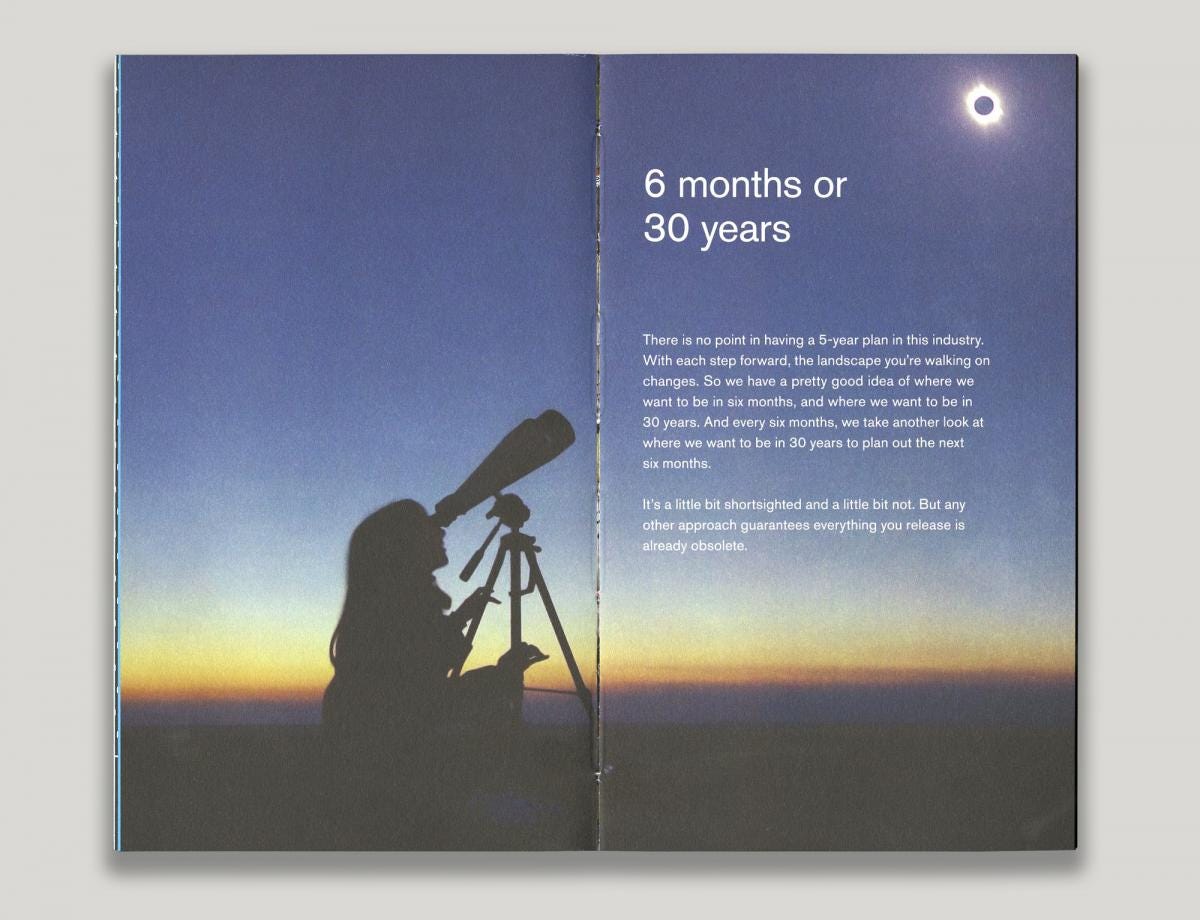
I think that 30-year view is also why Zuckerberg keeps insisting that Meta is a technology company. The catch is that almost everything we take for granted in modern life was once cutting-edge technology. So the only way to remain a technology company for decades is to stay at the bleeding edge every step of the way, and in Zuckerberg’s mind, I suspect that is what frontier models and Reality Labs are for. Unfortunately, our spreadsheets are mostly built for the next five years, and it can be exhausting for investors and analysts to keep up with all the twists and turns as Zuckerberg reshuffles priorities every six months to position Meta for the next 30 years.
I’m sure Zuckerberg himself would agree at this point that he scaled the Reality Labs bet way too much way too soon, and it has become a real blemish on his track record. The scale of capex required to stay in the frontier model race, without the commensurate frontier intelligence-driven revenue, also makes the current bet a bit uncomfortable for investors and creates a sense of déjà vu. And of course a bet, by definition, may not pay off on any time horizon. Still, I think Zuckerberg deserves the benefit of the doubt. Very few CEOs are willing, or able, to make long-term bold bets at all.
Owning Meta is ultimately a bet on Zuckerberg’s long-term vision. Given his singular importance and voting power, I have tried to observe and take into account how he carries himself in his personal life. From what we can see, Zuckerberg comes across as a family man. But I don’t know him, none of us really do, and who knows…it could be a public facade. Talking about any of this feels a bit like gossip, and yet admittedly, I have always paid some attention to it.
A while back I asked on Twitter how comfortable people would be owning a trillion-dollar business when almost nothing is publicly known about the CEO’s partner or spouse. I was thinking of Tim Cook. At the time, the internet had very little on his relationships, past or present, which surprised me for someone that prominent. The blowback was severe enough that I deleted the tweet (something I almost never do), and most of it was some version of “why do you care who sleeps with whom?” I understand where that comes from, and it is certainly Cook’s prerogative. But I am surprised that we don’t even want to acknowledge that it’s a bit unusual. To me it said something about how personal the privacy mantra is for Cook. Even when he mentioned a partner at his Apple farewell party in August, The Information reported that he referred to him only by his first name.
I have long suspected that the animosity between Apple and Meta reflects Cook’s personal conviction on privacy as much as any business logic, and I wondered what the relationship would look like with someone else running Apple. We may be starting to find out. Six weeks after John Ternus took over as CEO, Apple and Meta announced a collaboration to run Meta’s open-weight model on Macs, and Zuckerberg thanked Ternus by name. It’s too early to know but I find it hard to picture that exchange during the Cook years.
Cook is not the only CEO whose personal life I have paid attention to. Airbnb was a large position for me until recently, and one thing that gave me a tinge of discomfort (that I haven’t written about before) was that Brian Chesky is single. He has spoken openly about feeling isolated after Airbnb went public, and in a 2023 interview he said one of his biggest regrets would be not starting a family. It is healthy that a CEO can talk about his mental health struggle, and I wouldn’t want that to change. But Chesky is 45, and finding a partner and building a family are big questions in anyone’s life. I would rather my CEOs’ headspace not be clogged by such existential questions.
The pushback I got on that tweet was essentially that a CEO’s personal life is irrelevant to shareholders. Frankly speaking, I can imagine many people reacting very harshly about me pointing out Chesky’s marital status. The last few weeks should be a pretty good counterexample why I probably want to care while allocating my personal capital to these companies. You are free to ignore and decide that these things are completely irrelevant to a company’s long-term value. Of course, I know you could convincingly argue that Huang’s personal failings weren’t the “true” reasons he had to resign. But clearly those very failings gave his critics ample ammunition to use against him.
If people really are more important than ideas, then key man risk is probably very difficult to avoid, especially for companies operating at the cutting edge of technology. The same person whose 30-year view I am betting on is the person whose absence, or whose mistakes, would hurt the most. MBI Deep Dives has the same problem on a much smaller scale. I can’t make that risk go away, but I can at least have a plan for it. Well, whether that plan works will remain unknown to me…by design!
Subscribers get the daily journal and five+ years of Deep Dives, i.e. full-length analyses with financial models on 70+ companies. The daily is just how I think out loud between the Deep Dives!
Current Portfolio:
Please note that these are NOT my recommendation to buy/sell these securities, but just disclosure from my end so that you can assess potential biases that I may have because of my own personal portfolio holdings. Always consider my write-up my personal investing journal and never forget my objectives, risk tolerance, and constraints may have no resemblance to yours.
My current portfolio is disclosed below: